Tuesday, August 30, 2016
It's Natural (Disasters)
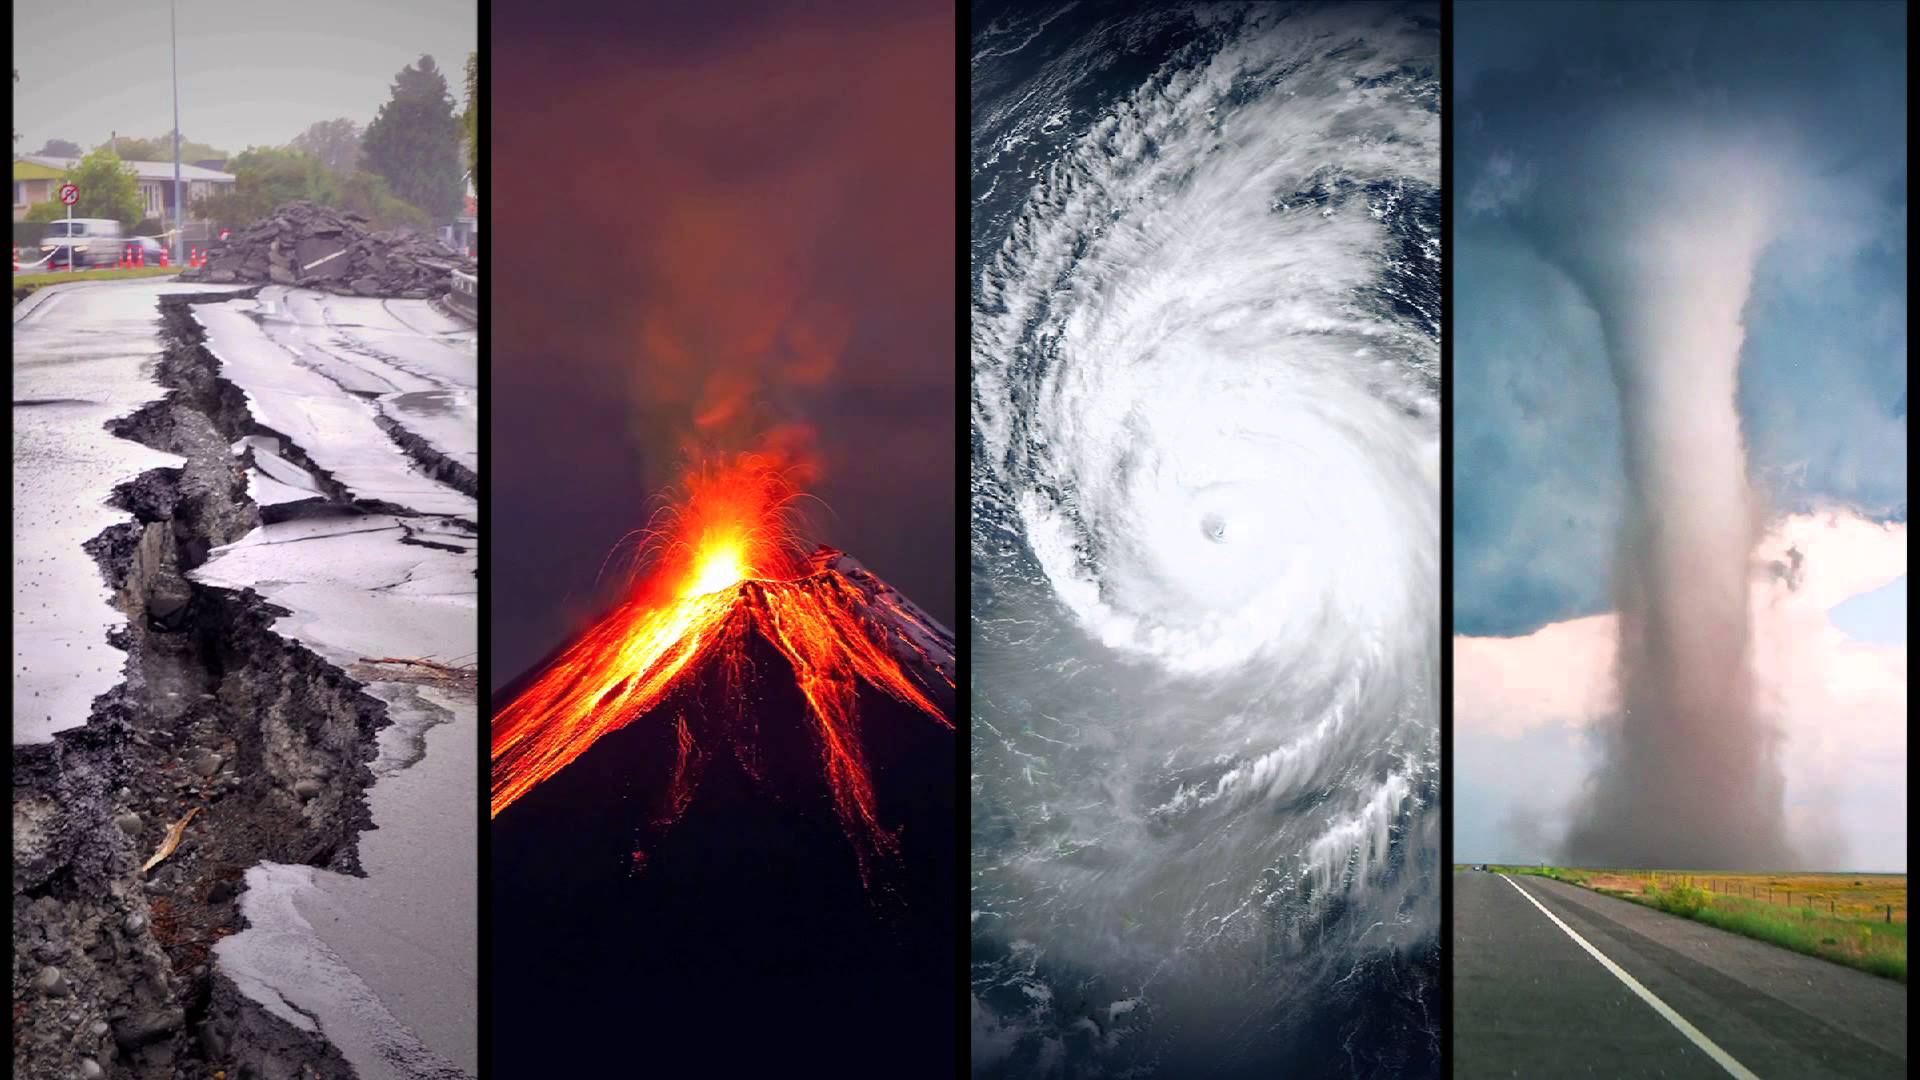
If you haven't felt the effects of the recent natural disasters through the country and world, tell me where you live and I'll consider the move. From flooding rains to wildfires to tornados it's proving to be a rough time for all. So how can you protect yourself?
First and foremost, it's important to have an emergency plan. Whether it's an emergency evacuation plan from your home or it's the best way to get to safety inside your home, make sure all your family members are on board. Remember that once you get to safety you might also need things, like food, blankets, flashlights, water, et cetera so be sure to have an emergency kit that is close to safety or easily accessible as you exit your house.
Now you are prepared to keep your family safe, how do you protect your things? Simple answer - Insurance. Make sure your broker or agent is familiar with the area and can help you sift through the risks you're bound to face. Should we consider flood insurance? Should you have wildfire protection? Should you have earthquake insurance? Should you have a separate deducible for wind or can we find a product without? There are so many things to consider depending on location, you'll never be able to address them all, but if you have a knowledgeable broker, you're ahead of the curve.
Before purchasing that insurance coverage, make sure you know the insurance company that will be paying your claim. Survey your social media friends, look at reviews online, talk to your broker. You want to make sure that the company you're working with has a good history of claims adjustment; that's what you're paying for after all, isn't it?
Good luck and be safe!
Photo courtesy of: http://eattomorrow.com/blog/wp-content/uploads/2015/08/natural-disasters.jpg
Tuesday, August 23, 2016
To Review or Not To Review?
I've been asked so many times over the last couple months, "When do I know I need an insurance review?"
If you're asking the question, the answer is probably "NOW!"
I thought I'd put together a quick list of life events that would cause exposure to change, which should then trigger you to consider having your coverages reviewed.
- Purchasing a new car: Whether it's your first or your 100th, you need to make sure coverage is appropriate.
- Moving: Buying a house? Renting an apartment? Doesn't matter - check your coverage. Different locations mean different exposures.
- New Bling: If you're getting engaged or celebrating a milestone anniversary, it's time to have your coverage checked.
- Getting Married: Between receptions and consolidating assets, it's a good time to make sure everything's in line.
- Getting Un-Married: Let's face it, with the divorce rate as it is in the US right now, there's a chance this happens, so let's make sure everyone is properly covered as we go through the process.
- Kiddos: Whether they're learning to drive, heading to college, setting up a Facebook; kids are more exposure than we can ever imagine.
- Liquidation Event: With cash on hand, lawsuits are looking for deep pockets.
- Retirement: A good time to make sure you haven't lost any coverages at work that were part of your property and casualty program.
- Estate Planning: New Trusts & LLC to preserve your wealth for the next generation? Your insurance policies MUST show these to have proper coverage.
- Home Renovations: Before, during and after - what should you know from an insurance perspective?
Let me know your thoughts. What should be added?
Friday, October 23, 2015
Incorrect replacement cost can cost you!
More often than not I get clients coming to me saying their
agent is over insuring their home.
“The
dwelling value is $X over what I paid for the home!”
“I
could never sell the home for that amount!”
“If I
had to rebuild this home, I could easily do it for $X amount. You wouldn’t have to purchase the land again…”
All very valid statements and reasonable arguments, but what
they don’t know is that there’s more to the story. Rebuilding a home is not the same as buying
an existing home, nor is the same as building a home from ground up.
Because of the common misconception, here is a list of
things that come into play with rebuilding a home after a total (or partial
loss):
·
Cost of
labor: Cost of labor is constantly increasing and an ever changing
market. Depending on the reason the home
was a total loss, there might be a shortage of labor (as there would be
following a hurricane, tornado or earthquake) or there might be no issues with
labor (as if there was a single home fire).
·
Demolition
and debris removal costs: People forget that after a total loss, there
typically are parts of the home that are still standing. These portions have to be torn down and
removed. Debris removal and demolition
costs can be costly.
·
Cost of
materials: Most insurance companies look to make you whole, some look to
put you back EXACTLY as you were before.
What’s the difference? If you had
marble flown in from Italy in your kitchen, some companies will replace it with
regular marble, some will have marble flown in from Italy. The cost of these materials can be very
different and some of these markets fluctuate much more often than others.
·
Building
permits: If you’re building a home (even if it’s rebuilding) you need to
apply for building permits. This takes
time, effort and money.
·
Architectural
drawings: Again, another thing that is necessary to rebuild a home. These also cost a pretty penny and take time.
So, no, maybe you cannot sell your home for what it would
cost to rebuild it and no, you do not have to purchase the land that your home
was already sitting on, but there are a lot of other factors that come into
play with replacement cost that may not matter in other situations.
Photo courtesy of:
Friday, October 16, 2015
Avoid the Rain, Buy an Umbrella
There are many websites online that show the US as having
the highest amount of lawyers per capita and some showing that the US is in
second place internationally. Regardless
of what statistic is completely accurate, I think it’s safe to say the US has a
ton lawyers. With a ton of lawyers comes a ton of law
suits.
So, what does this mean for you? You drive safely, have a fence around your
pool, always supervise children on your trampoline, are careful about who
operates your watercraft and even only let close family or friends go to your
second home. But with all this “stuff”
and all these “activities” comes exposure, and a lot of it.
We always recommend our clients have personal liability
coverage, regardless of who they are, what they have and how old they are. We are still all at risk. Because a bulk of the coverage comes through
a policy called an umbrella policy or excess liability policy, I’d like to
share with you some options that these policies may offer you.
·
Defense
costs: Some insurance contracts say that the defense costs are part of the
limit you choose and some pay the costs outside of the limit. So what’s better? If you have the choice, always chose outside
of the limit. This leaves the $1M, $5M,
$10M, etc. limit you choose to pay for damages to the other party or a
settlement and the $100K or more of legal fees you incurred are paid completely
separate.
·
Available
Limits: There is a myth in the
marketplace that individuals cannot obtain limits above $5M. This is not true. There are many carriers who offer limits well
above $5M and some all the way up to $100M.
Clearly everyone doesn’t need this high of limits, but I say with
confidence that all people should have an umbrella or excess liability limit of
some sort.
·
Employment
Practices Liability (EPLI): Sometimes individuals and families have people
who work for them directly. Now, to be
clear, I am not speaking about having a cleaning company come to your home or a
landscape company; I am talking about John Doe coming to your home to clean
regularly and when you pay John, the check reads his name or the cash is handed
to him. If this is true for you, you
might want to see if you can obtain EPLI coverage on your umbrella policy. Some companies offer this coverage as an
endorsement for a certain number of employees.
What this pays for is defense costs and settlements for employment
related matters. The best example I can
share is imagine you hire an individual to clean your home. This individual has family overseas and
notices you have a home phone. The
individual decides to call her family overseas one day for just a couple
minutes. This quickly becomes a routine
thing and you notice that your phone bill has skyrocketed. You promptly terminate the individual. The individual comes back complaining that
you fired her because she was foreign.
This coverage would protect you from a suit that individual may place
against you.
·
Non-for-Profit
Directors & Officers Coverage:
You’re trying to do some good for the world. You want to volunteer your time on a
board. Did you know there’s exposure
that goes along with this? The most
common response I hear is “Well the board has $1M of coverage for us.” Well, how many board members are there? Because this limit is split between all the
members and as soon as the limit is exhausted, anything else may be up to you
and the other board members personally. This
coverage can be added to some excess liability policies for certain types of
non-for-profit boards.
·
Excess
uninsured/underinsured motorists: Okay so you’ve done a great job choosing
your limit to protect your assets, but why should you trust that everyone else
has enough coverage or assets to pay for your medical bills if they hit
you? Answer? You shouldn’t. This coverage is available on some umbrella
policies up to $10M and is available to cover you and anyone in your vehicle if
you’re hit by an uninsured or underinsured driver. The coverage (just like other coverags on an
umbrella policy) sits above your auto policy, the uninsured/underinsured
motorist portion specifically.
·
Third
Party Liability: This is very similar coverage to the excess uninsured/underinsured
motorist coverage, but is an entirely different coverage. Let’s say you are at a friend’s house for a
pool party. Someone dropped some queso
on the pool deck and you’re quickly trying to make your way to get the last
mini corndog. You slip on the queso and
fall straight into the pool hitting your head on the way down. I can almost guarantee you will end up with
some medical bills, a hospital visit, potentially some lost time at work, if
not more. If that friend only has
$100,000 in homeowners liability, they may not have enough to pay for your
medical bills. That’s where this coverage
comes in. It will pick up (first dollar
paid out if necessary) you medical bills, lost wages, etc. What won’t this pay for? The corndog you never got to eat, but I’m
sure that’s the least of your worries.
The next logical question is how do I choose what limit is
right? Which of these coverages I really
need? That first question is another
topic to come. Stay tuned.
Photo courtesy of:
Tuesday, October 13, 2015
Commute to Work? Not Enough Sleep? Join the Club.
Fall is finally here in Chicago. The wind has picked up and the weather has
cooled down. My yard is full of leaves,
which means it’s time to start doing more yard work. With more work comes less sleep and I
am certainly a victim of this vicious cycle these days.
While I am fortunate to not have to commute by car to work, according
to a survey completed Statistics Brain published on 7/1/15, 75.7% of commuters
in the US commute alone by car.
According to a December 2013 study completed by Gallup, the average
American gets 6.8 hours of sleep. This
is far less than the recommended eight to nine hours of sleep. Okay, so what?
Less sleep and more driving is a dangerous combination. If you have a naturally curious mind and do
not watch MythBusters, I highly recommend it.
MythBusters confirmed the fact that driving while drowsy is more
dangerous than driving while drunk.
While I would not recommend either of them, how can we avoid driving
tired? (Yes, I admit that these things
can be hard to commit to, but I wouldn’t recommend risking your life by not
trying to take advantage of some of them.
Info courtesy of AAA.)
·
If you’re
tired, pull over. I am guilty of not
doing this and it is dangerous. The one
time that this happened to me that I can point out, I arrived home and was
terrified of all the things that could have gone wrong. It all could have been avoided by taking a
break at a gas station and walking around.
My life and the other lives in my car are not worth the ten minutes that
it could take to get out.
·
Get
enough sleep (DUH!). During the
week, this is hard. I understand! But no project, proposal, email is worth your
life. I promise.
·
Carpool. Here’s an easy fix and you’ll save some
money! Carpool with a
friend/coworker. You’ll have someone to
talk to and they can watch for your signs of fatigue.
·
Take a
power nap. This one might be my
favorite. Ever since I was young, I was
a napper. My parents can attest to the
fact that I slept well and often! If you’re
getting ready to drive home and you’re beat from the day, take a quick power
nap. Most offices have wellness rooms
these days where you can catch a quick couple minutes of sleep.
·
Know your
signs of fatigue. Make sure you’re
aware of when you’re tired and (most importantly) react to it. If you’re yawning, if you’re day dreaming, if
you’re drifting from your lane. Know
what they are and know what to do.
How can you make the road safer for the other individuals
who drive each day? You would want
people to do this for you, why shouldn’t you do it for them?
Info courtesy of:
Photo courtesy of:
Monday, September 28, 2015
Our New Home (Insurance Policy)
My husband and I recently purchased our first home! It’s an adorable little home (see above!) in the comfort
of a suburb of Chicago and we were beyond excited to move in! But as any homeowner knows, there are a
million things to do before you move in to that new home. Obviously, being a good “insurance nerd”,
after the loan was approved and all the paperwork was transferred, my first
reaction was, “We need good insurance.”
But what does that mean? Ask 100
people to define “good insurance” and you will get almost 100 different
answers.
Here are some of the things I considered when choosing
insurance:
·
Agent/Broker: This is probably the most
important decision when it comes to insurance.
This person is representing you to the insurance company. If you have a less than great agent or broker,
the insurance company may question things more often, may receive claims that likely
should not have been turned in because they are under your deductible, and not
to mention you may not get the service you expect or deserve year after year. Don’t discount how important this decision
is.
·
Replacement Cost: Replacement cost IS different than market
value. This is one of the hardest things
for individuals I speak with to comprehend.
Sometimes replacement cost is more and sometimes it is less than market
value. I have seen both situations, but
more often than not, it is more. Make
sure your agent or broker is utilizing some sort of tool to help them put
together this number. Some insurance
companies will come out to your home to do an appraisal, which will confirm
that the number you are placing on the policy is the most accurate.
·
Insurance Contract: Make sure your insurance contract
is the broadest you have. Some companies
offer earthquake, flood, back up of sump and sewer, etc. all right on the
homeowners policy. Consider the risks
you have in your area and look to protect those. And, if you’re new to the area, why not ask
your broker or agent what they see and what their clients are concerned
about? Also, make sure you have at least
replacement cost coverage! (See my post “Valuation
Battle: ACV vs. RC vs. ERC” from 12/30/13 for more details.)
·
Pricing: Price is always a consideration when
choosing coverage. While looking for
coverage, remember that every insurance company has a different target
market. Some companies want homes over
$1M in replacement cost, some companies are looking for clients with no claims,
some companies only want homes with alarms that are monitored. Brokers typically have access to more than
one company and can help you make a decision about which carriers are best, so
this is likely an easy way to explore the market.
·
Company: There is something to be said about
branding and customer experience of insurance companies. You want to be sure that if there is a claim,
your insurance company is going to work with you to get your claim resolved,
not against you.
·
Ownership of the Home: Did you title your home
in a trust or an LLC? It’s EXTREMELY
important to make sure that your company adds this entity as an additional insured. This provides liability coverage for this
entity should it be sued in the event of a liability claim. Not all companies can do this, so make sure
to check while going through the placement process.
There are so many other things to consider, but these are
what I found to be most important.
Happy home hunting!
Friday, September 25, 2015
A Diamond is a Girl's Best Friend
There aren’t many people I know who don’t like getting
something new and shiny – especially if it’s a beautiful tennis bracelet or a
great pair of diamond earrings. As the
saying goes, “A diamond is a girl’s best friend.”
Over the past three weeks I have run into multiple
individuals who are concerned about their jewelry collections and potential
losses associated with these items. What
are some of the (warranted) concerns I am seeing?
-
Chipped or missing stones
-
Mysterious disappearance of an item
-
One lost item of a pair or set
-
Theft
So – what is the best way to avoid or deal with these losses
before they happen?
-
Have your items regularly checked by a jeweler
(One recent client caught a horrible loss because the jeweler checked this item
every six months. If they had not done
this, it would have likely been years before they were able to recover the
damages.)
-
Get an in home safe that is bolted down (I can’t
tell you how many horror stories I have heard where the individual has a safe
but it’s not bolted. The thief takes the
entire safe and the whole collection is gone.)
-
Make sure your insurance policy includes pair
and set coverage (This is especially important for earrings. If one earring is lost or stolen, you want to
be sure you can replace both of them so they match exactly. This endorsement allows you to do that.)
-
Bring only enough jewelry for you to wear if you’re
traveling (There are some cases where you may need special items, but at the
risk of having them stolen or left behind, it’s always better to only bring
what you will wear to and from the airport.
There are numerous real life examples of individuals having their bags checked
by security and items fall out, or are never placed back in the bag by
TSA. Don’t allow this to happen to you.)
-
Have updated appraisals completed every five
years or so (With the value of precious metals and stones going up almost every
day, an item can easily appreciate in the course of a year. While there are some policies that build in
coverage for this so you can replace the item, many policies only place a
stated value coverage which does not allow any increased coverage for appreciation. These appraisals will give piece of mind that
you have the correct number assigned to this item and many times the jeweler
you bought the item from will update your appraisals without any cost to you. )
While insurance policies are great things, some of these
things are steps you can take to protect yourself. What other ways are you managing your risk?
Photo courtesy of: http://www.adweek.com/fishbowldc/files/2010/11/diamonds-1.jpg?red=dc
Subscribe to:
Posts (Atom)