Tuesday, September 20, 2016

Does my auto policy cover my rental car?


I'm picking up a rental car today for a road trip I have over the next couple days, which got me thinking...  I get asked at least once a month whether or not someone should purchase the insurance that the rental car company offers.  Like many things in insurance (and life), the answer is "it depends".

Most personal insurance companies (this is the company you use to insure the car you own) will cover liability of a rented car, and if you have physical damage listed on your policy (comprehensive and collision) it will also cover that.  So what are the other limitations?
  • Time: Rental cars are usually covered for 30 days in your care by your personal auto insurance.  Make sure you look at your policy contract to confirm, but we usually see 30 days.  So what happens after that 30 days is up?  No coverage.  Best advice is to turn the car in to the rental car company and rent another (or ask for the same one if you liked it).  This starts a new rental agreement and you'll have coverage from your personal auto policy for another 30 days.
  • Loss of Use:  If you're in an accident in the rental car, the car company can charge you loss of use.  Basically, they're asking for you to pay because they can no longer rent out the car.  There is almost no personal auto policy that will pay for loss of use to a rental car.  Check with the credit card companies you do business with to see if they offer some coverage.  If you pay for your rental car with that credit card, they may offer some of this coverage for you.
  • Deductible: Your personal auto policy usually has a deductible for comprehensive and collision coverages.  If you are in an at fault accident, you will be responsible for that amount before you auto insurance will pay.  This is another place to check with the credit card company that you intend to pay for the service with.  Sometimes they have some built in coverage.

If your credit card company will not offer coverage for loss of use and your deductible (or you do not have physical damage coverage on your auto on your personal auto policy) you may want to consider purchasing that coverage the rental car company offers (and then makes you sign if you decline).  Better to be safe than sorry, but your broker or agent should be able to help you work through the details of what your policy covers and what it does not cover.

Photo courtesy of http://blog.static.consumerbell.com.s3.amazonaws.com/wp-content/uploads/2012/09/Orlando-car-rental1.jpg

Tuesday, August 30, 2016

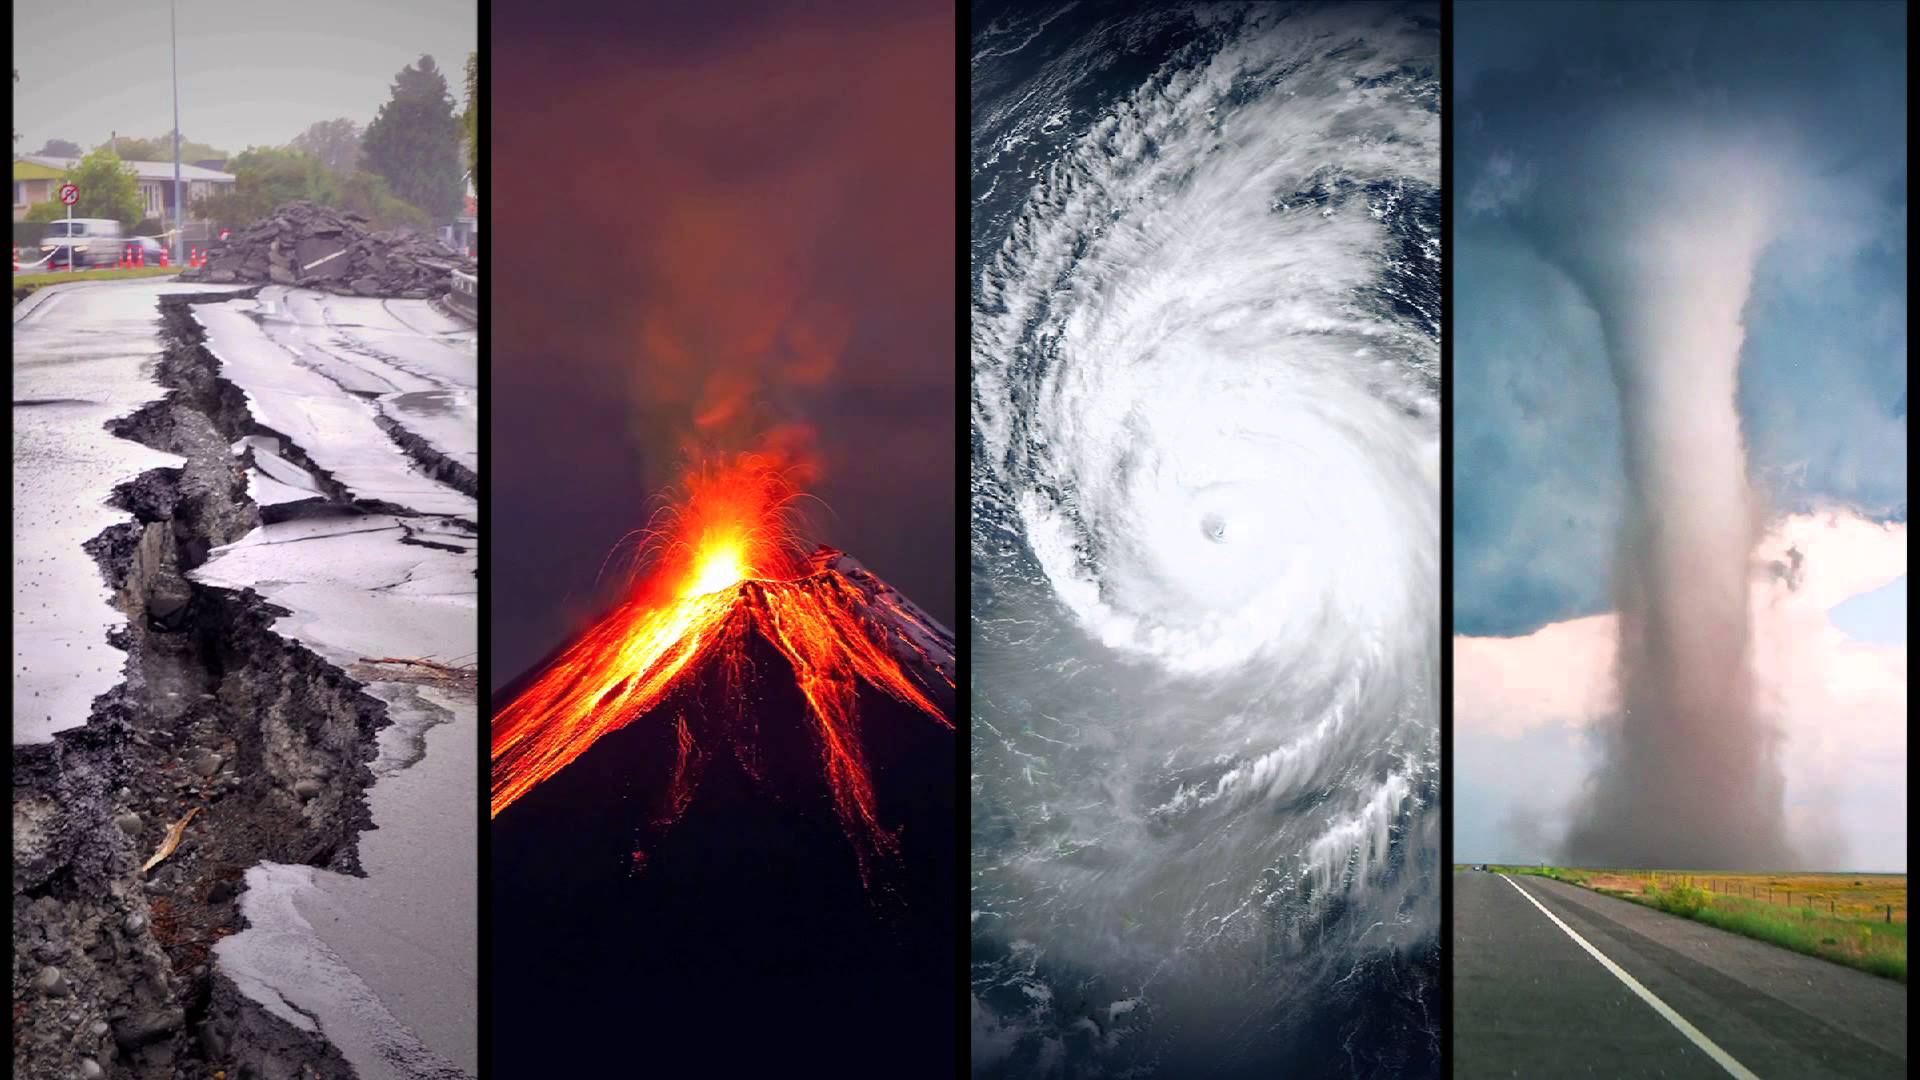
It's Natural (Disasters)


If you haven't felt the effects of the recent natural disasters through the country and world, tell me where you live and I'll consider the move.  From flooding rains to wildfires to tornados it's proving to be a rough time for all.  So how can you protect yourself?

First and foremost, it's important to have an emergency plan.  Whether it's an emergency evacuation plan from your home or it's the best way to get to safety inside your home, make sure all your family members are on board.  Remember that once you get to safety you might also need things, like food, blankets, flashlights, water, et cetera so be sure to have an emergency kit that is close to safety or easily accessible as you exit your house.

Now you are prepared to keep your family safe, how do you protect your things?  Simple answer - Insurance.  Make sure your broker or agent is familiar with the area and can help you sift through the risks you're bound to face.  Should we consider flood insurance?  Should you have wildfire protection?  Should you have earthquake insurance?  Should you have a separate deducible for wind or can we find a product without? There are so many things to consider depending on location, you'll never be able to address them all, but if you have a knowledgeable broker, you're ahead of the curve.

Before purchasing that insurance coverage, make sure you know the insurance company that will be paying your claim.  Survey your social media friends, look at reviews online, talk to your broker.  You want to make sure that the company you're working with has a good history of claims adjustment; that's what you're paying for after all, isn't it?

Good luck and be safe!

Photo courtesy of: http://eattomorrow.com/blog/wp-content/uploads/2015/08/natural-disasters.jpg

Tuesday, August 23, 2016

To Review or Not To Review?

Image result for thinking


I've been asked so many times over the last couple months, "When do I know I need an insurance review?"

If you're asking the question, the answer is probably "NOW!"

I thought I'd put together a quick list of life events that would cause exposure to change, which should then trigger you to consider having your coverages reviewed.
  • Purchasing a new car: Whether it's your first or your 100th, you need to make sure coverage is appropriate.
  • Moving: Buying a house? Renting an apartment?  Doesn't matter - check your coverage.  Different locations mean different exposures.
  • New Bling: If you're getting engaged or celebrating a milestone anniversary, it's time to have your coverage checked.
  • Getting Married: Between receptions and consolidating assets, it's a good time to make sure everything's in line.
  • Getting Un-Married: Let's face it, with the divorce rate as it is in the US right now, there's a chance this happens, so let's make sure everyone is properly covered as we go through the process.
  • Kiddos: Whether they're learning to drive, heading to college, setting up a Facebook; kids are more exposure than we can ever imagine.
  • Liquidation Event: With cash on hand, lawsuits are looking for deep pockets.
  • Retirement: A good time to make sure you haven't lost any coverages at work that were part of your property and casualty program.
  • Estate Planning: New Trusts & LLC to preserve your wealth for the next generation?  Your insurance policies MUST show these to have proper coverage.
  • Home Renovations: Before, during and after - what should you know from an insurance perspective?
While this list is not all inclusive, I hope it gives a good grasp on when to call your broker for a review; NOW.

Let me know your thoughts.  What should be added?

Friday, October 23, 2015

Incorrect replacement cost can cost you!


More often than not I get clients coming to me saying their agent is over insuring their home.

                “The dwelling value is $X over what I paid for the home!”

                “I could never sell the home for that amount!”

                “If I had to rebuild this home, I could easily do it for $X amount.  You wouldn’t have to purchase the land again…”

All very valid statements and reasonable arguments, but what they don’t know is that there’s more to the story.  Rebuilding a home is not the same as buying an existing home, nor is the same as building a home from ground up.

Because of the common misconception, here is a list of things that come into play with rebuilding a home after a total (or partial loss):

·         Cost of labor: Cost of labor is constantly increasing and an ever changing market.  Depending on the reason the home was a total loss, there might be a shortage of labor (as there would be following a hurricane, tornado or earthquake) or there might be no issues with labor (as if there was a single home fire).

·         Demolition and debris removal costs: People forget that after a total loss, there typically are parts of the home that are still standing.  These portions have to be torn down and removed.  Debris removal and demolition costs can be costly.

·         Cost of materials: Most insurance companies look to make you whole, some look to put you back EXACTLY as you were before.  What’s the difference?  If you had marble flown in from Italy in your kitchen, some companies will replace it with regular marble, some will have marble flown in from Italy.  The cost of these materials can be very different and some of these markets fluctuate much more often than others.

·         Building permits: If you’re building a home (even if it’s rebuilding) you need to apply for building permits.  This takes time, effort and money.

·         Architectural drawings: Again, another thing that is necessary to rebuild a home.  These also cost a pretty penny and take time.

So, no, maybe you cannot sell your home for what it would cost to rebuild it and no, you do not have to purchase the land that your home was already sitting on, but there are a lot of other factors that come into play with replacement cost that may not matter in other situations.

Photo courtesy of:

Friday, October 16, 2015

Avoid the Rain, Buy an Umbrella


There are many websites online that show the US as having the highest amount of lawyers per capita and some showing that the US is in second place internationally.  Regardless of what statistic is completely accurate, I think it’s safe to say the US has a ton lawyers.  With a ton of lawyers comes a ton of law suits.
So, what does this mean for you?  You drive safely, have a fence around your pool, always supervise children on your trampoline, are careful about who operates your watercraft and even only let close family or friends go to your second home.  But with all this “stuff” and all these “activities” comes exposure, and a lot of it.
We always recommend our clients have personal liability coverage, regardless of who they are, what they have and how old they are.  We are still all at risk.  Because a bulk of the coverage comes through a policy called an umbrella policy or excess liability policy, I’d like to share with you some options that these policies may offer you.
·         Defense costs: Some insurance contracts say that the defense costs are part of the limit you choose and some pay the costs outside of the limit.  So what’s better?  If you have the choice, always chose outside of the limit.  This leaves the $1M, $5M, $10M, etc. limit you choose to pay for damages to the other party or a settlement and the $100K or more of legal fees you incurred are paid completely separate.
·         Available Limits:  There is a myth in the marketplace that individuals cannot obtain limits above $5M.  This is not true.  There are many carriers who offer limits well above $5M and some all the way up to $100M.  Clearly everyone doesn’t need this high of limits, but I say with confidence that all people should have an umbrella or excess liability limit of some sort.
·         Employment Practices Liability (EPLI): Sometimes individuals and families have people who work for them directly.  Now, to be clear, I am not speaking about having a cleaning company come to your home or a landscape company; I am talking about John Doe coming to your home to clean regularly and when you pay John, the check reads his name or the cash is handed to him.  If this is true for you, you might want to see if you can obtain EPLI coverage on your umbrella policy.  Some companies offer this coverage as an endorsement for a certain number of employees.  What this pays for is defense costs and settlements for employment related matters.  The best example I can share is imagine you hire an individual to clean your home.  This individual has family overseas and notices you have a home phone.  The individual decides to call her family overseas one day for just a couple minutes.  This quickly becomes a routine thing and you notice that your phone bill has skyrocketed.  You promptly terminate the individual.  The individual comes back complaining that you fired her because she was foreign.  This coverage would protect you from a suit that individual may place against you.
·         Non-for-Profit Directors & Officers Coverage:  You’re trying to do some good for the world.  You want to volunteer your time on a board.  Did you know there’s exposure that goes along with this?  The most common response I hear is “Well the board has $1M of coverage for us.”  Well, how many board members are there?  Because this limit is split between all the members and as soon as the limit is exhausted, anything else may be up to you and the other board members personally.  This coverage can be added to some excess liability policies for certain types of non-for-profit boards.
·         Excess uninsured/underinsured motorists: Okay so you’ve done a great job choosing your limit to protect your assets, but why should you trust that everyone else has enough coverage or assets to pay for your medical bills if they hit you?  Answer?  You shouldn’t.  This coverage is available on some umbrella policies up to $10M and is available to cover you and anyone in your vehicle if you’re hit by an uninsured or underinsured driver.  The coverage (just like other coverags on an umbrella policy) sits above your auto policy, the uninsured/underinsured motorist portion specifically.
·         Third Party Liability: This is very similar coverage to the excess uninsured/underinsured motorist coverage, but is an entirely different coverage.  Let’s say you are at a friend’s house for a pool party.  Someone dropped some queso on the pool deck and you’re quickly trying to make your way to get the last mini corndog.  You slip on the queso and fall straight into the pool hitting your head on the way down.  I can almost guarantee you will end up with some medical bills, a hospital visit, potentially some lost time at work, if not more.  If that friend only has $100,000 in homeowners liability, they may not have enough to pay for your medical bills.  That’s where this coverage comes in.  It will pick up (first dollar paid out if necessary) you medical bills, lost wages, etc.  What won’t this pay for?  The corndog you never got to eat, but I’m sure that’s the least of your worries.
The next logical question is how do I choose what limit is right?  Which of these coverages I really need?  That first question is another topic to come.  Stay tuned.
Photo courtesy of:

Tuesday, October 13, 2015

Commute to Work? Not Enough Sleep? Join the Club.


Fall is finally here in Chicago.  The wind has picked up and the weather has cooled down.  My yard is full of leaves, which means it’s time to start doing more yard work.  With more work comes less sleep and I am certainly a victim of this vicious cycle these days.

While I am fortunate to not have to commute by car to work, according to a survey completed Statistics Brain published on 7/1/15, 75.7% of commuters in the US commute alone by car.  According to a December 2013 study completed by Gallup, the average American gets 6.8 hours of sleep.  This is far less than the recommended eight to nine hours of sleep.  Okay, so what?

Less sleep and more driving is a dangerous combination.  If you have a naturally curious mind and do not watch MythBusters, I highly recommend it.  MythBusters confirmed the fact that driving while drowsy is more dangerous than driving while drunk.  While I would not recommend either of them, how can we avoid driving tired?  (Yes, I admit that these things can be hard to commit to, but I wouldn’t recommend risking your life by not trying to take advantage of some of them.  Info courtesy of AAA.)

·         If you’re tired, pull over.  I am guilty of not doing this and it is dangerous.  The one time that this happened to me that I can point out, I arrived home and was terrified of all the things that could have gone wrong.  It all could have been avoided by taking a break at a gas station and walking around.  My life and the other lives in my car are not worth the ten minutes that it could take to get out.

·         Get enough sleep (DUH!).  During the week, this is hard.  I understand!  But no project, proposal, email is worth your life.  I promise.

·         Carpool.  Here’s an easy fix and you’ll save some money!  Carpool with a friend/coworker.  You’ll have someone to talk to and they can watch for your signs of fatigue.

·         Take a power nap.  This one might be my favorite.  Ever since I was young, I was a napper.  My parents can attest to the fact that I slept well and often!  If you’re getting ready to drive home and you’re beat from the day, take a quick power nap.  Most offices have wellness rooms these days where you can catch a quick couple minutes of sleep.

·         Know your signs of fatigue.  Make sure you’re aware of when you’re tired and (most importantly) react to it.  If you’re yawning, if you’re day dreaming, if you’re drifting from your lane.  Know what they are and know what to do.

How can you make the road safer for the other individuals who drive each day?  You would want people to do this for you, why shouldn’t you do it for them?

Info courtesy of:


Photo courtesy of:

Monday, September 28, 2015

Our New Home (Insurance Policy)


My husband and I recently purchased our first home!  It’s an adorable little home (see above!) in the comfort of a suburb of Chicago and we were beyond excited to move in!  But as any homeowner knows, there are a million things to do before you move in to that new home.  Obviously, being a good “insurance nerd”, after the loan was approved and all the paperwork was transferred, my first reaction was, “We need good insurance.”  But what does that mean?  Ask 100 people to define “good insurance” and you will get almost 100 different answers.

Here are some of the things I considered when choosing insurance:

·         Agent/Broker: This is probably the most important decision when it comes to insurance.  This person is representing you to the insurance company.  If you have a less than great agent or broker, the insurance company may question things more often, may receive claims that likely should not have been turned in because they are under your deductible, and not to mention you may not get the service you expect or deserve year after year.  Don’t discount how important this decision is.

·         Replacement Cost:  Replacement cost IS different than market value.  This is one of the hardest things for individuals I speak with to comprehend.  Sometimes replacement cost is more and sometimes it is less than market value.  I have seen both situations, but more often than not, it is more.  Make sure your agent or broker is utilizing some sort of tool to help them put together this number.  Some insurance companies will come out to your home to do an appraisal, which will confirm that the number you are placing on the policy is the most accurate. 

·         Insurance Contract: Make sure your insurance contract is the broadest you have.  Some companies offer earthquake, flood, back up of sump and sewer, etc. all right on the homeowners policy.  Consider the risks you have in your area and look to protect those.  And, if you’re new to the area, why not ask your broker or agent what they see and what their clients are concerned about?  Also, make sure you have at least replacement cost coverage!  (See my post “Valuation Battle: ACV vs. RC vs. ERC” from 12/30/13 for more details.)

·         Pricing: Price is always a consideration when choosing coverage.  While looking for coverage, remember that every insurance company has a different target market.  Some companies want homes over $1M in replacement cost, some companies are looking for clients with no claims, some companies only want homes with alarms that are monitored.  Brokers typically have access to more than one company and can help you make a decision about which carriers are best, so this is likely an easy way to explore the market.

·         Company: There is something to be said about branding and customer experience of insurance companies.  You want to be sure that if there is a claim, your insurance company is going to work with you to get your claim resolved, not against you.

·         Ownership of the Home: Did you title your home in a trust or an LLC?  It’s EXTREMELY important to make sure that your company adds this entity as an additional insured.  This provides liability coverage for this entity should it be sued in the event of a liability claim.  Not all companies can do this, so make sure to check while going through the placement process.

There are so many other things to consider, but these are what I found to be most important.   Happy home hunting!

Friday, September 25, 2015

A Diamond is a Girl's Best Friend


There aren’t many people I know who don’t like getting something new and shiny – especially if it’s a beautiful tennis bracelet or a great pair of diamond earrings.  As the saying goes, “A diamond is a girl’s best friend.”

Over the past three weeks I have run into multiple individuals who are concerned about their jewelry collections and potential losses associated with these items.  What are some of the (warranted) concerns I am seeing?

-          Chipped or missing stones

-          Mysterious disappearance of an item

-          One lost item of a pair or set

-          Theft

So – what is the best way to avoid or deal with these losses before they happen?

-          Have your items regularly checked by a jeweler (One recent client caught a horrible loss because the jeweler checked this item every six months.  If they had not done this, it would have likely been years before they were able to recover the damages.)

-          Get an in home safe that is bolted down (I can’t tell you how many horror stories I have heard where the individual has a safe but it’s not bolted.  The thief takes the entire safe and the whole collection is gone.)

-          Make sure your insurance policy includes pair and set coverage (This is especially important for earrings.  If one earring is lost or stolen, you want to be sure you can replace both of them so they match exactly.  This endorsement allows you to do that.)

-          Bring only enough jewelry for you to wear if you’re traveling (There are some cases where you may need special items, but at the risk of having them stolen or left behind, it’s always better to only bring what you will wear to and from the airport.  There are numerous real life examples of individuals having their bags checked by security and items fall out, or are never placed back in the bag by TSA.  Don’t allow this to happen to you.)

-          Have updated appraisals completed every five years or so (With the value of precious metals and stones going up almost every day, an item can easily appreciate in the course of a year.  While there are some policies that build in coverage for this so you can replace the item, many policies only place a stated value coverage which does not allow any increased coverage for appreciation.  These appraisals will give piece of mind that you have the correct number assigned to this item and many times the jeweler you bought the item from will update your appraisals without any cost to you. )

While insurance policies are great things, some of these things are steps you can take to protect yourself.  What other ways are you managing your risk?
 

Friday, February 7, 2014

Inside Job


Would you let someone into your home with permission to dig through your things without your direct supervision? People do it all the time with new housekeepers, construction workers, painters, etc. These people are usually recommended by friends or "reputable" companies, but the risk of theft still arises. 

Recently I've dealt with two situations. The first where someone was having some renovations completed and two of his jewelry items were stolen by the workers totaling about $22,000 (luckily one of the items was recovered). The second where this lady was very busy and was in desperate need of having her home cleaned before a large party. She didn't have time to supervise the cleaning lady she hired. A couple months later she realizes a significant amount of her jewelry is missing. 

You're probably thinking "But I'm smarter than that, I hire trustworthy people." Or better yet, "I'm home when they're working. What do I have to worry about?"

The truth of the matter is we have to depend on other people to help, but it's hard to be sure we can trust them. 

So how should you protect yourself? 
1) Hire from a recommended and backed service who does background checks on all their employees. 
2) Use referrals from close friends. 
3) Protect yourself with valuable articles coverage for your more expensive items that might be at home outside of your supervision. 
4) If you hire someone that is paid directly by you (an individual that does not work for a contract company or a cleaning company) make sure to do your research and reach out to your agent to see if you have employment practices liability coverage for domestics available to you. 
5) Always keep your valuables out of sight. 
6) Periodically spot check the work of the people coming to your home. 

Have you been victimized? What do you do to protect yourself? I want to hear from you!

Friday, January 31, 2014

The Risk Management and Agent/Broker Battle

So I recently had someone ask me if I had read any good articles about insurances agents thinking like risk managers. This really got me to thinking. After about a full hour of deep (Google) research I had come to the conclusion that it was up to me to put this together. 

Risk managers are typically used on the commercial side. It's an investment that a firm uses to lessen risk. They do this through the transfer, mitigation and avoidance of risk. So the question being posed to me of a personal lines agent thinking like a risk manager isn't something that I had consciously thought about. Subconsciously this is something I do on a daily, and even hourly, basis. 

The idea is that we should find the most cost effective, fully encompassing program that best meets the values and lifestyle of the client. The only way to do this is to have regular discussions with the client about how their assets and needs are changing. 

But what does this really mean? Every agent needs to be able to carefully listen for underlying themes and be creative. It's going to look different for every client, as it should. 

My best suggestions are
1) know the contracts of the companies you represent, inside and out. 
2) never be fearful to ask a client if they're happy with what you've put together for them. 
3) offer all possible options for a program. 
4) do your research before spitting out a yes or no answer. 
5) inform your client of the market, of the coverages they have and tell them what they're paying annually. 
6) learn as much as you can through continuing education classes. 
7) listen to your client. Don't provide them with the same program you give everyone, they don't want it and it's not good business. 
8) provide suggestions for ways that clients can completely avoid or mitigate risks. 

What are you're thoughts? How do you think like a risk manager? Maybe you're not even in the insurance field but there are certain things you do. 

Monday, December 30, 2013

Valuation Battle: ACV vs. RC vs. ERC


Maybe you’ve spoken to your insurance agent and they’ve mentioned some sort of loss valuation, such as actual cash value.  My assumption is you left that discussion thinking, “Great!  My loss will be paid.”  But what does this actually mean? When it comes to loss valuations, there are three common valuations: actual cash value, replacement cost and extended replacement cost.  Let’s break these down…


Actual Cash Value

Actual cash value provides the least amount of coverage in most cases.  Actual cash value is replacement cost minus depreciation.  I’ll go into replacement cost in a second, but depreciation is whatever percentage that your items, homes, cars, etc. are said to lose in value each year, just because they’re a year older and their “useful life remaining” is coming to an end.  Thus, if you have items that appreciate in value or don’t lose any value, you may not end up with a settlement that you like. 


Let me give you an example – In the type of clients that I work with on a day to day basis, they like their cars.   I have many clients with collector Aston Martins or Ferraris.  The idea of this is that these vehicles appreciate in value and if they hold them for a couple years, they’ll come out with more money than they invested in the car in the first place.  For easy round numbers, let’s say a car was purchased in 2008 for $100,000.  Now, it’s 2014 and there is a total loss because the driver lost control of the car.  In 2014 the car might cost $120,000 to purchase, but because it is now 4 years older there might be a depreciation of $40,000.  Thus, the loss settlement will be $80,000 and you will not be able to replace the car.  Obviously, this is a generic example, but this happens often when it comes to homes.


Replacement Cost

Replacement Cost is pretty simple.  The valuation would be what it would cost to replace the item with a similar item today.  There is no “depreciation” taken into account, because the item might be more or less to replace today depending on what it is.


Here’s another example for you – I have an iPad that was purchased for $500 in 2010.  In 2013, there is a fire in my home and the iPad is completely damaged.  I find my same iPad purchased in 2010 for $200 because it is three years later and other, newer models have come out.  My insurance company will give me the $300 to replace it.


In the example above regarding the high end vehicle, in 2014, the insurance company would likely pay up to $120,000 (depending on how the contract reads) or the limit shown on the policy if it is less than $120,000.


Extended Replacement Cost

Extended replacement cost is similar to replacement cost, but it is not capped at the limit shown on the policy.


Here’s my last example for you – I purchase a beautiful $500,000 home, my dream home, which I insure for $500,000 with extended replacement cost.  Being on the gulf, we see hurricanes from time to time.  Well, a hurricane sweeps through and takes out my beautiful home.  I’m devastated, but I have extended replacement cost.  What this means is the other costs associated with my home, that didn’t come along with the previous owner such as debris removal, cost of labor increasing, cost of materials increasing (all because most of the other homes in my neighborhood were also destroyed), are now relevant.  So a year and a half and $700,000 later, my home is back standing.  The insurance company paid out that total $700,000 even though my policy only showed $500,000.


If we go back to our first example regarding the high valued vehicle, we would be able to add in other costs that go with obtaining the vehicle, even though the replacement cost is set at $120,000.  This would include things like delivery charges, taxes, etc.  So maybe in reality, it costs $135,000 with all those extra costs and this valuation would pay that amount.


Not all companies offer extended replacement cost and the ones that do will want to go to your home, or see an appraisal or bill of sale for your item in order to verify their valuation is correct.  But, if your company offers it, it’s definitely the broadest loss valuation.


Another challenge for you… Check out your policy, talk to your agent.  The last thing you want is to find out which of these loss valuations your policy uses when you have a loss.  Insurance contract surprises are not good at the time of loss.

Saturday, November 30, 2013

Say My Name: Named Insured Status

What's in a name? As it relates to an insurance policy, a lot.

If you're actually to pull out your insurance contract and read the definitions, you'll find a definition for "named insured". This is basically the person named on the policy as the owner. It can be multiple people (usually a husband and wife), a single person or a company (in the case of a commercial policy). 

So, why is it important to make sure the named insured is correct on the policy? A lot of policies limit or even eliminate coverage for non residents. So think about this, a family lives in Texas. The husband has a job transfer that temporarily relocates him to Florida for a year. He moves and his wife and kids continue to live in Texas until he returns. While he is not living in the house, if he is not listed as a named insured on the insurance policy, he could be excluded from liability coverage. This is also true in divorces or separations. If a spouse moves out, there could be a gap in coverage as it relates to liability and property coverage. 

The other place to closely review named insured status is as it relates to vehicles. Who owns the car? What entity owns the car? That is who the named insured should be. So, if you use a company that bundles all the autos in the household into one policy, make sure that the named insured matches the owner on the title of the car and if it doesn't, then you'll probably need to have your agent or broker write a separate policy each of the vehicles owned by separate owners or entitles. 

And finally, what about umbrella or excess liability coverage? The umbrella policy should match the underlying policies. This will insure that coverage will be seamless in the event of a large liability loss. 

In some cases, you will put homes or cars in the name of a trust, LLC or LP. Some carriers will cover this under a personal lines policy, but will list an individual or married couple as the named insureds and the trust, LLC or LP as an additional insured. There is a difference between additional insured and named insured, but that is for another time. What's important in this post is being sure both spouses are listed as the named insured regardless of the additional insureds. 

So, moral of the story? Review your insurance policy. Make sure the owners match up with the named insureds and both spouses are listed. There are special cases where only one spouse will be listed, and your insurance agent or broker can speak to you more about this. 

Wednesday, November 6, 2013

Ignorance is Not Bliss: Homeowners Special Limits of Liability


What is your most valuable real asset? I'm not talking about your family, your personality, your job, etc. Some people might answer that question by saying their home or their auto, but what about items that are smaller or easier to be lost, stolen or destroyed? For example jewelry, fine arts, oriental rugs, antique furniture, silverware...?

These items typically have limited coverages on a homeowners or renters policy. While you see a limit for contents or personal property, within the contract you will find special, lower limits for these categories. I'm going to have a lot of insurance agents or brokers upset with me because I might be creating more work for them, but I challenge you to pull out a copy of your contact and look for a section called "special limits of liability." This will provide you with exactly the limits that your policy is subject to; if you can't find it reach out to you agent or broker, if they can't find it or you don't know who they are, it might be time to find a new agent or broker.

Now let's talk about a solution. Obviously you want to keep your valuable items out of harms way (jewelry in a safe or vault, fine art and furniture out of direct sunlight, maintain an active centrally monitored fire and burglar alarm), but is there an insurance solution? Are you surprised to hear there is? Probably not. 

It's called a collections/valuable articles/personal article/inland marine policy/rider/floater. Whatever the insurance company decides to call it, they all serve the same purpose, to protect those items (and more) mentioned above. These policies are typically inexpensive depending on the category of the item you're looking to cover and a lot of times you'll find that they are available without a deductible. 

There are two ways to provide coverage for these items, blanket or scheduled. 

Scheduled coverage is where each item is specifically listed on the policy with a description and a value (usually determined by an appraisal or bill of sale). So, if you were to encounter a covered loss, the company will pay up to the limit that is shown to replace it (some companies offer a cash out option where you are not required to replace the item, and some companies offer an extended replacement cost option if the value of the item appreciates). It is especially important to remember that scheduled items should have updated appraisals every couple of years as the value of art, gold, silver, etc. is increasing dramatically year over year at this point in time. 

Blanket coverage, while not offered by every company, lists a limit for each of the chosen categories. You are not required to advise anything to the insurance company about the items that are being covered under this type of collections policy, but there may be a per item limit. What this means is if you have a per item limit of $10,000 and you have a covered loss of an item worth $12,000, the company will only pay the first $10,000 for any single item (not a single occurrence). Some companies have a higher rate for blanket coverage, so typically if you're looking to pay less premium you'll want to look toward scheduled coverage. 

My guess is following this information, you've got some work to do! Good luck! Please feel free to post any questions, comments or concerns. 


Photo curtesy of
http://www.123rf.com/photo_5855575_closeup-of-wooden-treasure-chest-with-valuables.html

Friday, October 25, 2013

Constructing Safety: Home Construction Risk Management


Construction season is at different times of the year for different parts of the country, but in Texas (specifically southeast Texas) it's October. Within the last month I've had two friends and four clients who have started construction projects for a new home or renovations on an existing home. So let's address these two situations separately because for risk management and insurance purposes they will be handled that way. 

First, let's start with new homes. You're looking for a contractor that you can trust. How do you know they're good? How do you know they are properly covered?
1) Ask them for recommendations. Most contractors, especially if they're good, will have clients who can or have provided them with a recommendation, just as you would see with a job interview process.
2) Request to drive past another job site if they have one. This way you can see what the quality of the work is while it's in progress. 
      Have they left tools out overnight? 
      If the site's unattended, did they leave windows open? 
      If work is being done, are proper safety measures being taken? 
      Are the workers wearing gloves while stapling? 
      Is there someone holding the ladder while another person climbs to the roof?
      Where is paint or stain stored when it's not being used? (This is a huge fire hazard. I personally have see a situation where the house was almost complete but due to poor storage of paint in the garage, the entire home burned down.) 
3) Ask to see certificates of liability insurance providing accurate limits and waivers of subrogation. The accurate limits speaks for itself, but what is a "waiver of subrogation"? According to Investopedia, a waiver of subrogation "prohibits the insurer from attempting to seek restitution from a third party who causes any kind of loss to the insured." And now a translation, if there's a loss (typically liability loss) while the home is being constructed, the general liability insurer will not look to the homeowner for payment of the claim, rather the insurance company will pay the claim. This protects you if the builder or insurance company seems to think you're at fault for whatever reason. 
4) Do a "Google" search of the company. A lot of times you can find reviews online and while some may not be valid and most may be negative, this can give you a better idea of any issues they have had in the past. I don't recommend leaving it at that though. Ask the contractor about it, why they had these issues and what they have done to avoid them moving forward. Issues are going to happen and the true character of a company will show through in how they dealt with it. 
5) Make sure you have a builder's risk or course of construction policy in place. I'm not going to go into the differences between those policies at this time, but you are able to secure this coverage through the builder or you may even be able to do so through your insurance broker. 
      (One note to protect yourself if you have a builder's risk policy, if you start moving ANY personal property in the home - a couch, a bed, a lamp, etc. - the insurance contract from a builder's risk policy I voided and the insurance company will not pay the claim. Make sure the day you begin to move anything in you have a homeowners policy in place.)

Now let's look at updates to an existing home. What should you consider? Obviously all the information above applies in this situation as well, but there are a couple of other things you should consider. 
1) If you are living in a portion of the home during construction, make sure you keep your doors to that portion of the home locked and your alarms active. While you hope you can trust the workers who are updating your home, I recently had a client who had a significant amount of jewelry stolen from a construction worker doing updates. Additionally, you want to be sure if there is a fire in the portion you're living in the alarm sounds so you're able to get out safely. 
2) Regardless of how much or little work you're doing, talk it through with your insurance broker. If your just painting or updating a room, they'll likely tell you that your policy is okay, but if you're adding square footage, moving walls or making structural changes, they'll likely have to notify the underwriter for approval. If you don't talk to your broker and there's a loss, it's very possible the insurance company could deny to pay the claim. So then you've been writing checks for nothing and no one likes that!
3) Once construction is completed, review your homeowners dwelling limit shown on the insurance policy. It's likely that it needs to be adjusted. Most companies can help you out with this. This is a very important step because a lot of the carriers will require your home to be insured for at least 80% to value to avoid any penalties if there's a loss by something called a coinsurance clause. 

Now that you've got an idea of a couple items to consider, get to work! Your hose isn't going to build or repair itself!

As always, please share your thoughts and comments.  Happy construction season southeast Texas!


Some information sourced from
http://onswipe.investopedia.com/investopedia/#!/entry/,5228a3d9da27f5d9d0177eb2

Photo curtesy of 
http://adamcowherdconstruction.com/services/home-builders-springfield-mo/

Monday, October 21, 2013

Avoiding a Haunting this Halloween


Halloween is a fun time of year! You have the opportunity to be something or someone you're not, and who can overlook those adorable children and dog costumes! But, you're not reading this post to hear about all the wonderful things surrounding Halloween, are you? Didn't think so. 

What are your exposures during Halloween? For your kids, your home, yourself, your friends? What have you overlooked that if you take five minutes or less to prepare for can make October 31st and the days before more enjoyable?

So it's the weekend before Halloween when all the adults participate in their Halloween festivities (don't worry, suggestions for kids activities are coming next). What should you think about before you're dressed up in your costume at the bar or a friend's house?
-Regardless of if you're drinking water or whiskey water, don't set your drink down! This gives the opportunity for someone who may be looking to ruin your night to do so. 
-A cute guy (or gal) comes up to you with a drink they purchased or made for you. Respectfully decline. Drinking anything that you didn't see made or poured directly from the can/bottle leaves you open to something that you don't want being mixed in. 
-During this time, you'll also see a lot of "adult punches" that we're made by the host. My suggestion? Stay clear. Whatever you brought or bought is much safer than the sugary vat of alcohol sitting on the table. 
-You're at the party, it's coming to the end, so how are you going to get home? Make sure you have a plan beforehand. Call a cab, have a DD in place, walk (if you're close enough), but DO NOT get in your car to drive if you've had anything more than a coke. The last thing you want is to ruin you're costume by having it stuck in the back of a police car. 
-Say you've made your way to a bar crawl or are headed to your next destination, cross at crosswalks only and be sure you're alert to oncoming cars. You may have made good decisions in not driving, but not everyone is as smart and proactive as you. 
-Don't drink TOO much. Need I expand? You're smart enough to figure out the consequences of this one. 
-Lastly, stay with a group of friends. Ending up in an unfamiliar place with people you don't know is not the kind of "Halloween spook" you were looking for. 

Okay, you've had your fun, and now it's time for the kids to get in their adorable costumes and collect some candy! (Of course it's not for you, although if you're lucky you'll sneak in a couple pieces after they're tucked in bed!) What should you think about?
-If you are going to be leaving the house so you can walk the neighborhood with your kids, make sure your alarm is set. You can leave candy on the front doorstep, but leaving a dark home on a night where teens are looking for trouble, can be more trouble than you're asking for.
-Stay with your kids. Obviously there is a time where they're going to want to go on their own with their friends, but there should be an adult not too far away just to keep an extra eye on the group. 
-Because it's getting dark so early these days, be sure your kids have reflective tape or part of their costume is made with reflective material so cars can see them. The last thing you want is a close call when one of the kids is running to a house across the street to get the "KING SIZED CANDY BARS EVERYONE IS TALKING ABOUT".
-On that note, if you're driving on Halloween, be alert. Kids are running throughout the neighborhood, and it can be dangerous for you and them.
-I know some families like to stay traditional and use candles in their beautifully carved pumpkins, but I recommend considering the substitute flickering lights. These provide much less of a fire hazard and they actually appear pretty real!
-If you have a dog, be sure he is tied up. Regardless of how friendly or obedient your dog is, that 99th time the door bell rings or someone knocks on the door might just be enough for him. It's a scary time for dogs when they're seeing people in costumes and someone is constantly at the door. The last thing you want is to be part of the statistic that says dog bites account for over one third of homeowners liability claims. 
-If you're in a colder climate, make sure the kiddos (and yourself) are wearing something that is warm enough. Growing up in Chicago, my costume always consisted of a winter jacket under some adorable pumpkin, or M&M costume.
-As always, be sure to check candy wrappers prior to letting kids dig in. If you've received a homemade treat it's probably best to file that in the trash no matter how cute it looks. 
-Finally, make sure the kids don't eat too much candy. They've got plenty of time to eat it, challenge them to see how long they can make their stash last. A sugar induced stomachache is the worst!

Most of all, the goal is to have fun! I hope you've learned a little something from my tips. If you have any to share, please comment on this! Collaboration from prior experiences or other thoughts can only make this year that much more enjoyable!

Happy Halloween!

Information sourced from
Insurancejournal.com

Photo curtesy of 
http://www.ymcastlouis.org/carondelet-park-rec-complex/events/halloween-hullabaloo-2

Thursday, October 10, 2013

Red Hot: Fire Prevention Tips


More than 3,400 people are killed in home fires each year, most of which are preventable. 

In honor of national fire prevention week, let's have a discussion to raise awareness of this fact. The age old story is of a homeowner who leaves a candle burning and leaves the home.  Or where a lit cigarette starts a small fire that ends up spreading to a neighbors house. In fact just this week Houston, someone was smoking a cigarette on their balcony of an apartment complex. When they went inside the cigarette was obviously still lit. By the time the fire department was able to get the fire under control, twelve units had been completely burned. And to think it was completely preventable...

So what can you do to minimize the risk of a fire in your home and protect your assets, starting with the obvious?
     - Always blow out candles if you are going to sleep, leaving the home or cannot sit in the same room with it. 
     - Always make sure your cigarettes, when done, are in an ashtray and completely out. Pour some water on it to be sure. 
     - Make sure working smoke detectors are in every room. 
     - Keep fire extinguishers in your home where every family member has access to it and knows how to use it. 
     - Create an escape route for your family and practice it. If you have kids this can be an especially fun time to get them active while making sure they know what to do if there's a fire. 
     - Have your furnace inspected before every winter to ensure it is working properly. 
     - Have your water heater inspected every year to insure it's working properly. 
     - When cooking, be sure to wear tight fitting clothing that will not easily dangle into a fire or on a burner. 
     - Do not leave food on the stove or in the oven unattended. 
     - After lighting a match run it under cold water for five seconds to ensure it is no longer burning before disposing of it. 
    - Do not plug too many electrical wires into a single outlet at one time. 
    - Do not leave space heaters on overnight or when unattended.  

If a fire is preventable, there is no reason we shouldn't do everything to do so. Ultimately an insurance policy will replace all your goods, but lives cannot be replaced. I encourage you to take every precaution moving forward and challenge you to sit down this weekend with your family to come up with a plan should a fire start. 

Remember - Only you can prevent home fires. 


Some information found via the following sources 
http://www.firesafetytips.com
http://www.redcrossdelmarva.org/home_fires.pdf
http://www.usfa.fema.gov/citizens/home_fire_prev/

Photo curtesy of 
http://www.hicaliber.biz/uncategorized/3611/